
A First-Time Buyer’s Guide to Dubai Off-Plan Luxury
From choosing a neighbourhood to checking payment plans and purchase documents, a practical guide to finding your first off-plan luxury home in Dubai.
Buying your first home in Dubai brings an exciting question into focus: what would you like everyday life to look like? Perhaps it is a city apartment close to your working day, a quieter setting beside nature, or a home where the waterfront becomes part of the routine.
With an off-plan purchase, you also need to understand what happens between choosing that home and receiving the keys. The floor plan matters, but so do the payment dates, ownership documents and commitments in the contract. This guide brings those decisions together, with Prestige One projects to explore along the way.
1. Why Dubai Off-Plan Luxury Appeals to First-Time Buyers
An off-plan home is purchased before it is completed. Depending on the development and availability, buying at this stage can offer a choice of layouts, floors and outlooks, alongside a payment schedule spread over agreed dates or construction milestones.
The appeal is not simply a lower starting payment. It is the opportunity to choose a home around how you intend to live. A well-positioned desk, useful storage or a balcony you will genuinely use can matter more than an impressive list of facilities.
There are trade-offs. You cannot inspect the finished apartment at the point of purchase, completion dates may change, and future prices or rental income are not guaranteed. Compare the full purchase cost with suitable completed homes rather than assuming every off-plan apartment comes at a discount.
2. Understand Ownership, Registration and Residency
Check the ownership rights for the specific property
Foreign buyers can purchase freehold property in designated areas of Dubai. Freehold and time-limited leasehold rights are different arrangements, so confirm the rights attached to the exact unit, not just the neighbourhood. The British Embassy’s property-buying guidance recommends checking eligibility to buy in the chosen area and obtaining appropriate independent advice.
Allow for registration and ongoing costs
Registration is not free. DLD’s initial-sale registration service lists a combined 4 per cent of the sale value, shown as 2 per cent for the seller and 2 per cent for the purchaser, plus additional fees. Confirm the allocation in your agreement and obtain an itemised cost statement before committing.
Your budget should also allow for applicable administration and financing charges, service charges, utilities, insurance and maintenance. Ask a qualified adviser about any tax obligations that apply to your personal circumstances, including obligations outside the UAE.
Treat residency as a separate eligibility check
DLD’s property-investor Golden Visa service describes a 10-year renewable residence permit for qualifying property investment of at least AED 2 million, subject to its requirements and approval. Bedroom count is not the qualifying test.
Do not assume that reserving an off-plan unit automatically secures residency. Confirm the applicable route, property stage, payment evidence and documentation with the relevant authority before making residency part of your purchase decision.
3. Choose a Development Around Your Daily Life
Start with a normal weekday, not the showroom visit. Where do you travel, who shares the home, and which spaces would make that routine easier? Use the same questions for every property on your shortlist.
- Location: check current journeys to work, schools and everyday services. Keep proposed infrastructure separate from connections available now.
- Layout: compare usable living space, bedroom privacy, storage and furniture placement. Our apartment layout guide offers a practical starting point.
- Amenities: prioritise facilities you will use and ask how their operation will be reflected in service charges.
- Delivery: review the developer’s completed work and dated progress records. Compare the contract specification with marketing imagery.
- Affordability: map every instalment against your resources, including the final balance and costs beyond the property price.
4. Explore Prestige One Projects That Match Your Priorities
These developments offer different starting points for a conversation, rather than a promise that one property suits every buyer. Ask the team to confirm current availability, specifications, prices and purchase terms for your chosen unit.
- For a city-focused routine: explore FAUCHON Résidences in Jumeirah Garden City. Its Parisian-inspired residential concept gives the address a distinctive character; assess the location against your own daily journeys.
- For a calmer family setting: consider Sanctuary Residences in Meydan Horizon. The project’s nature-facing setting and range of one-, two- and three-bedroom residences provide options to compare with your household’s needs. Explore the wider Meydan destination alongside the individual floor plans.
- For branded waterfront living: discover Hilton Residences Dubai Maritime City. Look beyond the brand to the layout, shared spaces and services included in the specific offering.
- For an island address: explore Seaside by Prestige One in Dubai Islands. Assess the waterfront setting on its own merits, without assuming a particular rental return.
- For a compact home with shared amenities: compare the studio and one-bedroom options at The Boulevard in DLRC. Check usable space and current transport options rather than assuming it offers the lowest entry price or a nearby Metro connection.
5. Build a Financing Plan Before You Reserve
A developer payment plan and a bank mortgage are not interchangeable. A payment plan sets out when the purchase price is due to the developer; a mortgage is a separate lending agreement that requires approval. Neither removes the need to understand the full commitment.
For a payment plan, request the booking amount, every instalment, the final balance and any post-handover terms in writing. There is no single schedule that applies to all Prestige One projects. Check what happens if the construction timetable changes or a payment is late.
If borrowing is part of your plan, obtain personalised guidance from a regulated lender or qualified mortgage adviser. Eligibility, the required deposit, rates and fees depend on the lender, borrower and property. Do not assume a mortgage will be available at handover simply because you can afford the first instalment.
Keep a contingency reserve. Funding a deposit with a credit card or personal loan adds debt and should not be treated as a cash-free shortcut to home ownership.
6. Follow the Purchase from Reservation to Handover
The precise sequence depends on the transaction. For a direct off-plan purchase, use the following as a discussion checklist with the developer and your independent adviser.
- Verify the development: check the developer, project registration and project escrow account details through DLD or Dubai REST before transferring funds. DLD’s buyer and development FAQs explain project escrow accounts and how to check reported construction progress.
- Review the reservation terms: confirm the exact unit, price, booking payment and cancellation or refund conditions. Keep copies of signed documents and receipts.
- Read the sale and purchase agreement: check the specification, payment schedule, anticipated completion, delay provisions, variation clauses and resale conditions. Seek independent legal advice on anything unclear.
- Confirm initial registration: obtain evidence of the unit’s provisional registration through Oqood. DLD’s initial-sale service states that the signed contract must be registered in the provisional register within 90 days of signing.
- Pay according to the contract: independently verify payment instructions and retain a record of every instalment. Follow dated construction updates, while recognising that photographs alone do not establish contractual completion.
- Prepare for inspection: review the handover notice and arrange a snagging inspection where applicable. Record defects and clarify the process for addressing them.
- Complete the handover requirements: confirm the outstanding balance, applicable charges, registration documents, utilities and access arrangements. Request clear instructions for title documentation and after-sales support.
If you are purchasing an existing buyer’s off-plan interest rather than buying directly from the developer, the process can differ. Ask about assignment restrictions, approvals and any NOC required for that specific transaction.
7. Look Beyond the Purchase Price
The first year of ownership involves more than receiving the keys. Service charges, furnishing, maintenance and utility costs all affect how comfortably the home fits your budget. Request available estimates and understand which figures remain provisional before completion.
If you may rent the property later, distinguish gross rent from income after costs. Vacancy periods, management charges, maintenance and financing can change the result substantially. Neither a luxury specification nor a freehold address guarantees a rental yield or future resale price.
Choose a property you understand well enough to hold through changing circumstances. The floor plan, location and ownership costs should make sense without depending on a forecast increase in value.
8. Your Practical Checklist and Next Steps
- Set a total budget that includes fees, future instalments and a contingency reserve.
- Shortlist two or three homes and compare the same layout and location criteria.
- Request current project information and arrange an available viewing or virtual tour.
- Verify registration and escrow details before making payments.
- Obtain financing guidance before relying on future borrowing.
- Review the agreement independently and confirm residency eligibility separately.
- Keep your payment records, contract and registration evidence together.
Your first purchase does not need to begin with a perfect understanding of every term. It should begin with the right questions and enough time to have them answered. Speak with the Prestige One team to explore current availability, request project-specific payment details and arrange the next step.
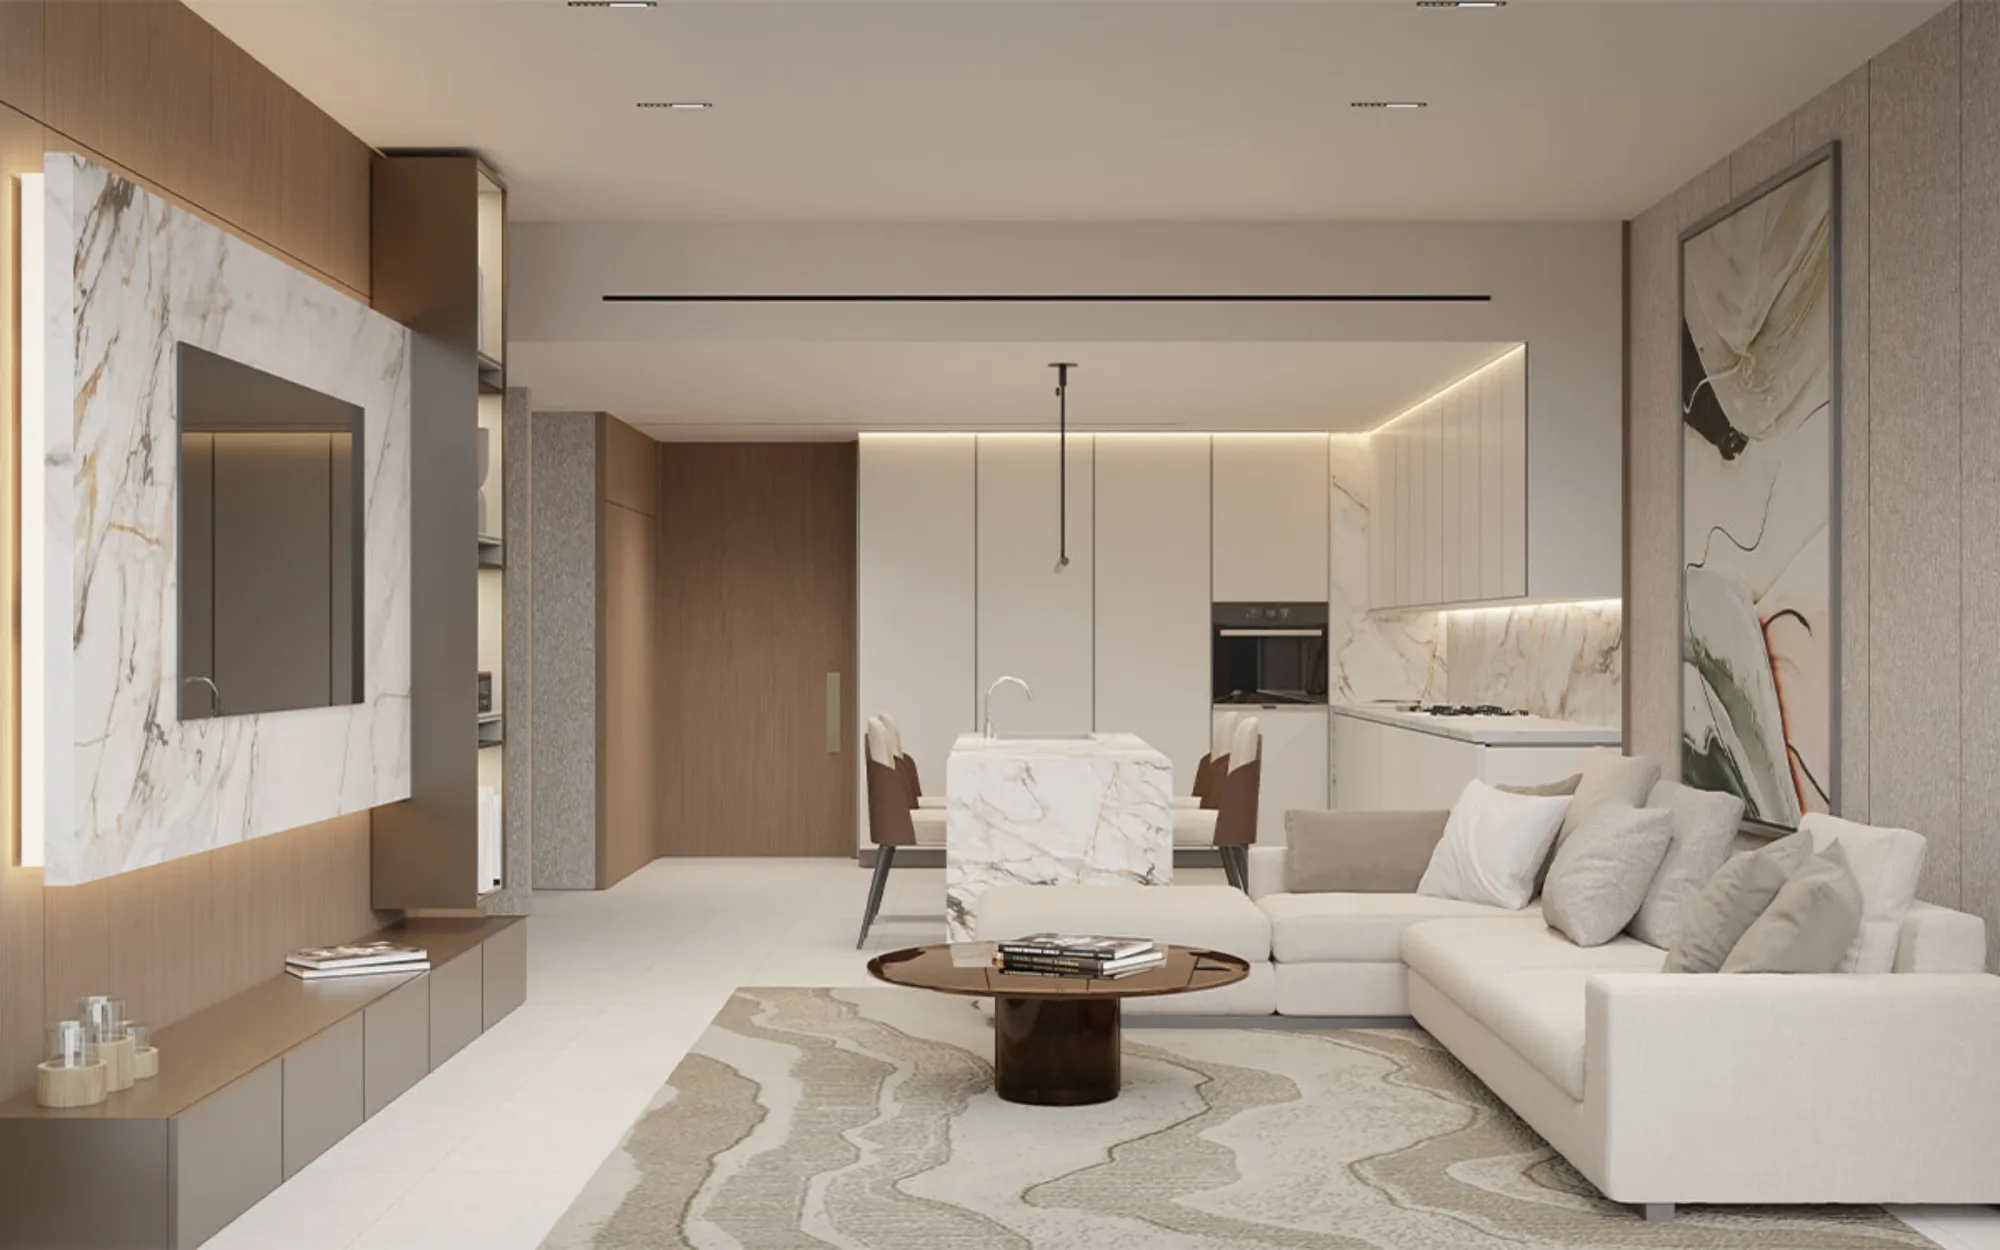
The featured image is a Seaside apartment visualisation, not a photograph of a completed home or a specification for every unit. This guide provides general information, not personalised legal, tax, immigration or financial advice. Official requirements and project terms should be reconfirmed before purchase.
More stories
Discover what comes next
Explore our developments or speak with our team for more information.